Seller Beware of Certain Offers — Part One
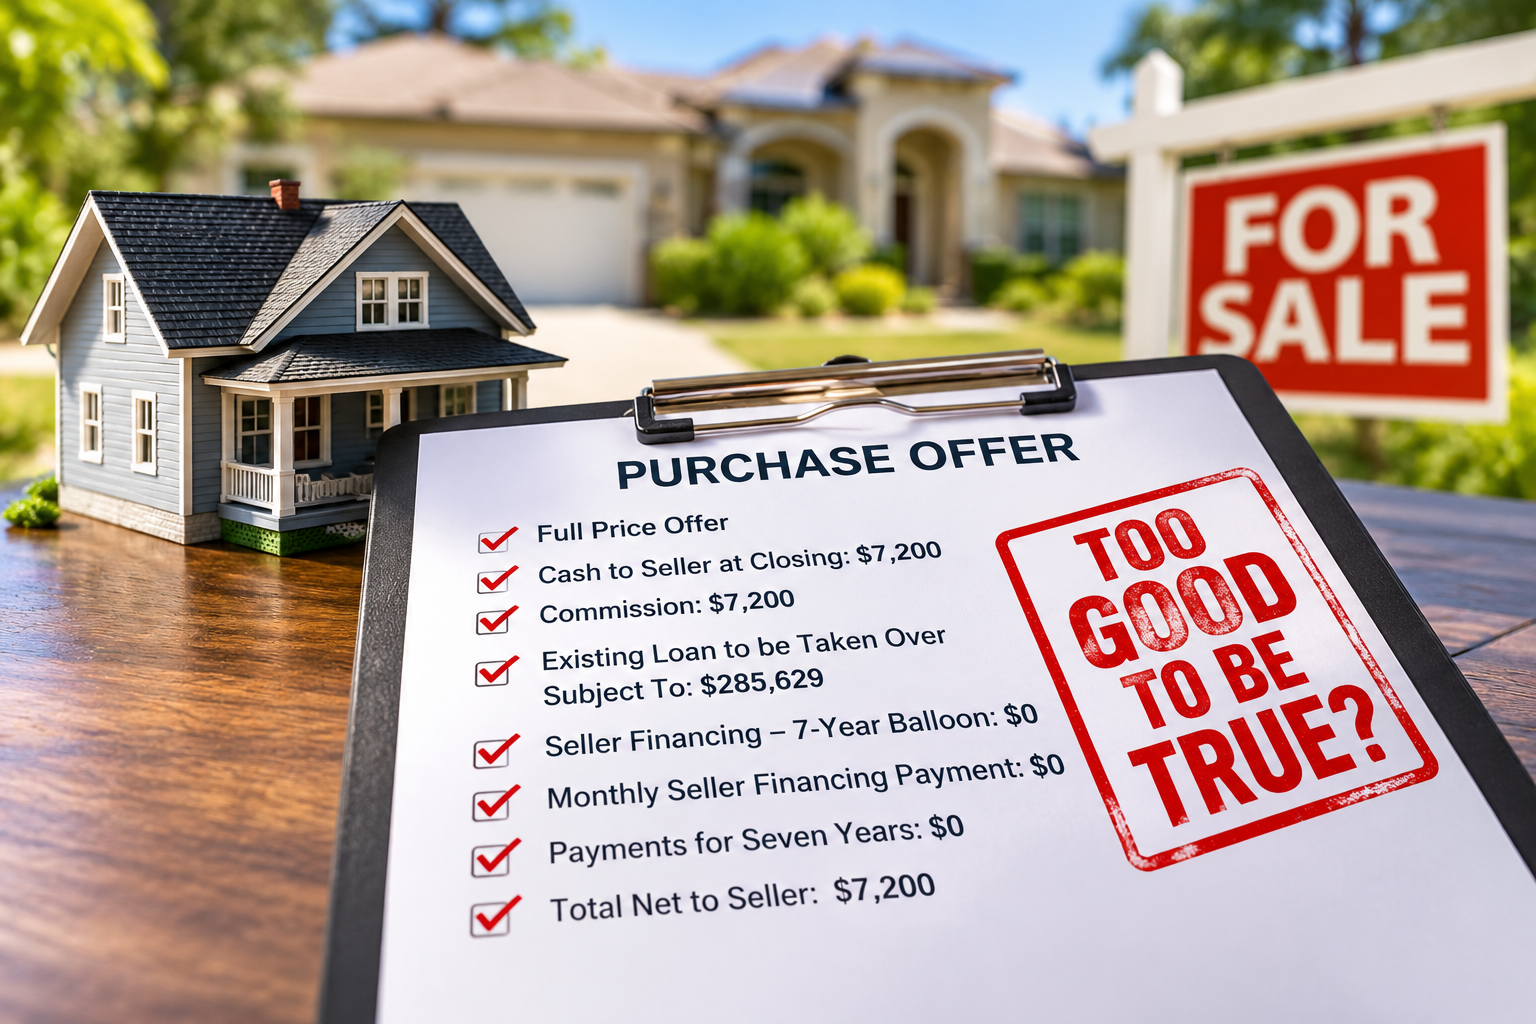
Can a full-price offer on your home actually be a bad offer?
Absolutely. Some offers look very attractive when you first see the purchase price, but when you look closely at how the buyer intends to finance the transaction, the seller may be taking on far more risk than they realize.
A Real Offer I Recently Received
I recently received an offer on one of my listings that is a good example of why sellers need to understand all the terms of an offer—not just the purchase price.
On the surface, the buyer was offering full price.
Here is essentially how the offer was structured:
Cash to seller at closing: $7,200
Commission: $7,200
Existing mortgage to remain in place “subject to”: $285,629
Seller financing — 7-year balloon: $0
Monthly seller-financing payment: $0
Payments on that seller financing for seven years: $0
Stated net cash to seller at closing: $7,200
When I saw the offer and looked at what my seller was actually being asked to accept, my response was pretty simple:
“LOL, no thank you.”
Someone unfamiliar with this type of financing could look at the words “full-price offer” and think they are getting a great deal.
But the details tell a very different story.
What Does “Subject To” Mean?
In a typical “subject to” transaction, the buyer takes ownership of the property subject to the seller's existing mortgage.
That is very different from the buyer formally assuming the seller's mortgage.
The existing mortgage can remain in the seller's name. The buyer may agree to make the payments, but the original borrower can remain responsible to the lender.
That distinction is extremely important.
The seller has transferred ownership of the house, but the seller may not have eliminated the mortgage obligation associated with that house.
The Seller Could Still Carry the Financial Risk
This is where I believe sellers need to be extremely careful.
If the buyer stops making the mortgage payments, who is the mortgage company going to look to?
The person whose name is still on the loan.
That could be the seller.
Late or missed payments could potentially damage the seller's credit and financial standing. The seller may also have difficulty qualifying for another mortgage because the existing debt can still affect the seller financially.
Meanwhile, the seller no longer owns the property.
Think about that for a moment.
You could give someone ownership of your house while the mortgage used to purchase that house remains in your name.
What About the Buyer's Ability to Pay?
Another concern is that a transaction structured this way may not involve the same lender underwriting that you normally see when someone applies for a traditional mortgage.
With traditional financing, a lender typically examines the buyer's credit, income, assets, debts and ability to repay the loan.
If the buyer is simply taking title subject to an existing mortgage, the existing lender has not necessarily approved that buyer to take over the seller's loan.
That means the seller needs to understand exactly who is taking ownership of the property and how that buyer intends to make the payments.
What Happens If the Mortgage Company Finds Out?
There is another major issue sellers need to understand.
Many mortgages contain what is known as a due-on-sale clause.
Depending on the loan and circumstances, transferring ownership of the property without paying off the existing mortgage may give the lender the right to accelerate the loan and demand payment of the remaining balance.
That doesn't mean every lender will automatically do so.
But sellers should understand that the possibility exists.
Imagine selling your home, receiving only a relatively small amount of cash at closing, transferring ownership to someone else, and then discovering that the mortgage company wants the outstanding loan balance paid.
That is a risk a seller needs to understand before signing the contract, not afterward.
Full Price Doesn't Always Mean a Good Offer
This is why I tell sellers that the highest purchase price is not necessarily the best offer.
You have to look at the entire contract.
How much money are you actually receiving?
How is the buyer financing the purchase?
Is your existing mortgage being paid off?
Are you being released from your financial obligation?
What happens if the buyer doesn't make the payments?
What happens if the lender exercises its rights under the mortgage?
Those questions can be far more important than the number written at the top of the offer.
My Advice to Sellers
I'm not saying that every creative-financing transaction is automatically bad. Different transactions can make sense under different circumstances.
What I am saying is this:
Know exactly what you're agreeing to.
If someone wants to purchase your home while leaving your mortgage in place, I believe you should understand the contract, the loan documents and the potential consequences before agreeing to anything. Depending on the transaction, that may mean speaking with a real estate attorney, your lender, a qualified tax professional or other appropriate professionals before signing.
As a real estate agent, part of my responsibility is helping my sellers recognize terms that deserve a much closer look.
A contract can say full price and still expose the seller to substantial risk.
Final Takeaway
Don't judge an offer by the purchase price alone.
Sometimes the most important part of an offer isn't how much the buyer is offering. It's how the buyer plans to pay for it—and what obligations the seller will still have after closing.
If you're selling a home in Jacksonville, Mandarin, St. Johns, St. Augustine, Nocatee, Fleming Island, Jacksonville Beach, Neptune Beach, Atlantic Beach or Ponte Vedra Beach and receive an offer you don't fully understand, I'd be glad to help you look at the terms and understand the questions you should be asking.
Michael Nobles
CrossView Realty